
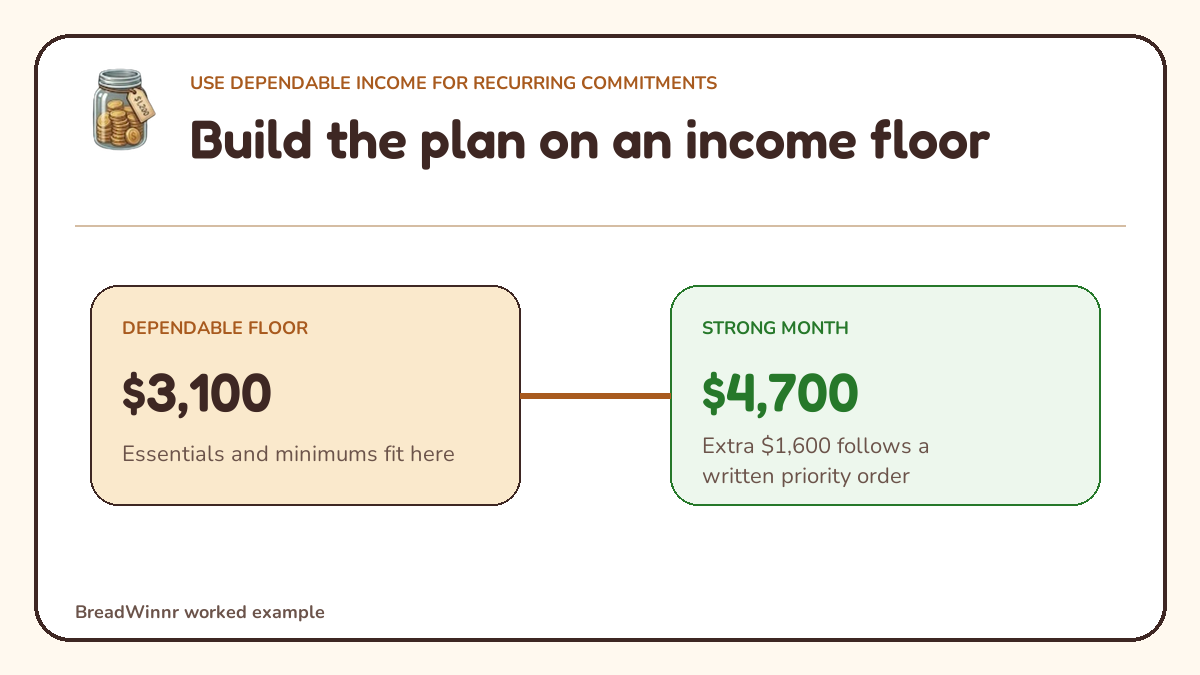
Use a conservative income floor for recurring commitments, then create a priority list for money above that floor. In a six-month test with income from $2,900 to $5,200, using $2,900 as the planning floor supports $2,650 of core costs and leaves a $250 base margin.
This guide responds to people whose monthly income changes enough that a fixed average produces frequent shortfalls.
Start here: a practical action plan
- List at least six months of take-home income and identify a conservative planning floor.
- Fit housing, food, utilities, transport, insurance, and minimum payments inside that floor.
- Write an ordered list for income above the floor before a high month arrives.
- Review the floor after a lasting income change, not after one unusually good month.
- Using average income when several recent months fell below it.
- Adding recurring bills that only a high-income month can support.
- Treating tax money or business expenses as personal take-home pay.
Choose a floor you can defend
List at least six months of actual take-home income. This worked dataset is $3,100, $4,500, $2,900, $5,200, $3,600, and $4,100. The average is $3,900, but committing to $3,900 would fail in the $2,900 month.
For this test, $2,900 is the floor because it is the lowest observed month. A seasonal worker may need 12 or more months and may choose an even lower figure. The floor is a planning choice, not a forecast.
| Month | Take-home income | Amount above $2,900 floor |
|---|---|---|
| 1 | $3,100 | $200 |
| 2 | $4,500 | $1,600 |
| 3 | $2,900 | $0 |
| 4 | $5,200 | $2,300 |
| 5 | $3,600 | $700 |
| 6 | $4,100 | $1,200 |
Fit recurring commitments below the floor
In the test, housing, utilities, food, transport, insurance, and minimum debt payments total $2,650. That leaves $250 below the floor. If core costs exceeded $2,900, the plan would need a larger starting buffer, reduced commitments, or a lower-cost arrangement.
Do not use the six-month average to sign up for a new fixed payment. The average includes strong months that may not repeat on schedule.
Write an order for income above the floor
When actual income is $4,500, the $1,600 overage needs a sequence. One example is: restore any bill buffer, fund annual costs, add to emergency savings, make extra debt payments, then fund wants.
The order prevents every strong month from becoming a new lifestyle baseline. Use percentages or fixed targets, but define them before the money arrives.
Update the floor after evidence changes
Review the rolling history quarterly and after a contract, rate, or season changes. Remove business revenue that is not personal take-home pay, and reserve taxes before treating self-employment cash as spendable.
Across this test, budgeting at the $3,900 average would create a $1,000 shortfall in the lowest month. Budgeting at $2,900 avoids that specific mismatch and exposes the need to decide what higher-income dollars should do.
Frequently asked questions
Should I budget variable income using an average?
An average can help forecast annual income, but it may be unsafe for recurring monthly commitments. A conservative floor based on lower observed months usually gives the base budget more resilience.
How many months should I review?
Start with at least six months. Use 12 or more when work is seasonal, commission-heavy, or affected by annual cycles. Exclude amounts that were unusual and unlikely to repeat.
What is an income floor?
An income floor is a conservative amount used to fund recurring obligations. It is not a guarantee. It is a planning boundary chosen from actual history and current work conditions.
What should I do in a high-income month?
Follow a written priority order. Common steps are restoring a cash buffer, funding irregular bills, adding emergency savings, paying extra debt, and then increasing optional spending.
How do taxes fit into a self-employed budget?
Treat money reserved for taxes as unavailable for household spending. Estimate obligations from appropriate tax guidance or a qualified professional, then build the personal income floor from the remainder.
What if income falls below the floor?
Use the cash-flow plan for essential obligations, reduce flexible spending, draw from a designated income buffer if available, and update the floor if the decline reflects a lasting change.
Sources and review notes
The calculations and scenarios in this guide are original BreadWinnr worked examples. We recalculated each example and checked that its parts match the stated total. Official sources support the financial concepts. Forum links document the reader problem that prompted the guide and are not treated as financial authority.
- CFPB: Your Money, Your Goals toolkit
- CFPB: Assess your spending
- Forum discussion: budgeting when monthly amounts fluctuate widely
Read our research, testing, corrections, and source policy.
This guide provides general financial education. It does not account for your complete financial, tax, legal, or contractual situation.
Make the example yours.
Use the 50/30/20 budget calculator to try a different starting point.