
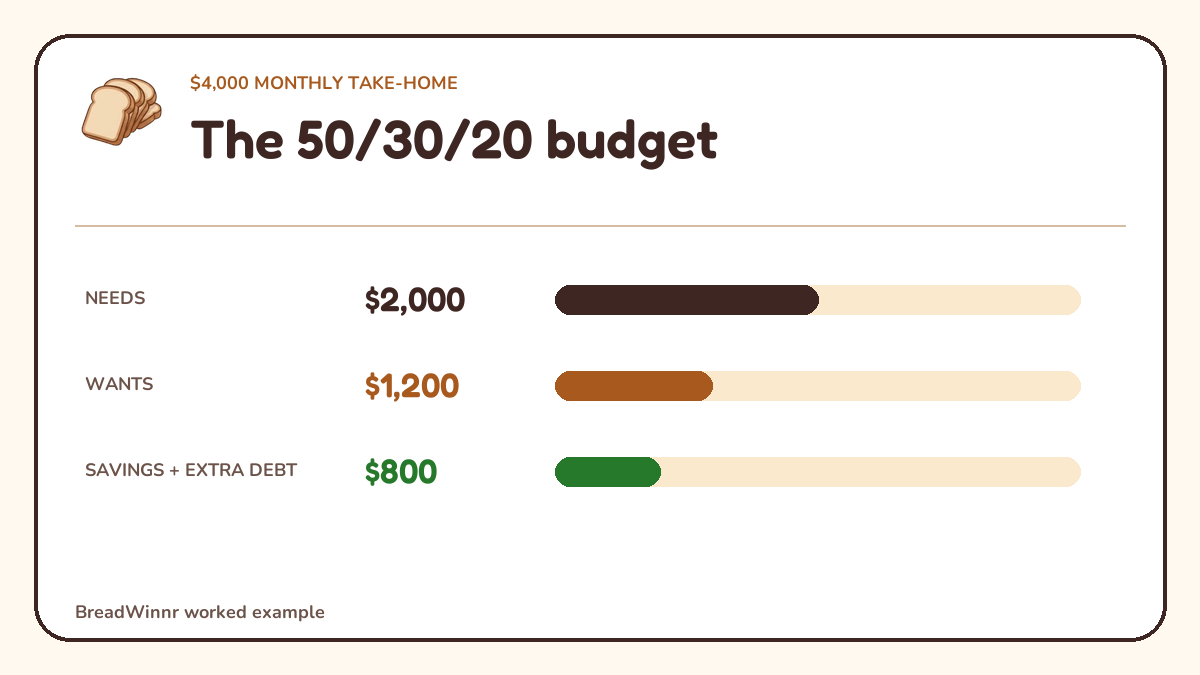
The 50/30/20 budget assigns 50% of take-home pay to needs, 30% to wants, and 20% to savings and extra debt payments. With $4,000 a month, that gives you $2,000, $1,200, and $800. Treat those numbers as a first draft, then compare them with your actual costs.
Start here: a practical action plan
- Download the last full month of checking and credit card activity.
- Use take-home pay after payroll deductions, then total needs, wants, and savings separately.
- Compare your real percentages with 50%, 30%, and 20%. Keep the real numbers even when they miss the guideline.
- Change one category at a time and confirm the final plan still adds to your full take-home pay.
- Counting a payroll retirement contribution again after it was already removed from take-home pay.
- Calling an essential expense a want just to make the percentage look better.
- Using the monthly total without checking whether cash is available before each bill date.
Start with the number that actually arrives
Use monthly income after taxes and payroll deductions. A salary figure from an offer letter can be much larger than the money available in your checking account. For this example, imagine someone receives two $2,000 paychecks every month. Their starting number is $4,000.
If you are paid every two weeks, two paychecks per month and an annual monthly average are different numbers. There are usually 26 biweekly paychecks in a year. Choose the approach you can keep consistent, and plan separately for when the extra checks arrive. With variable income, use an amount you can reasonably rely on rather than your best month.
The three buckets, in dollars
Multiply $4,000 by each share. The result is a framework for deciding where the money should go, before individual categories make the plan more detailed.
| Bucket | Monthly amount | Examples |
|---|---|---|
| Needs · 50% | $2,000 | Housing, groceries, essential transport, minimum debt payments |
| Wants · 30% | $1,200 | Dining out, entertainment, optional subscriptions |
| Savings & extra debt · 20% | $800 | Emergency savings, other goals, debt payments above minimums |
Give each expense one home
Some categories contain both needs and wants. The internet connection you need for work and a premium entertainment bundle can sit on the same bill. Splitting the bill can be more useful than forcing the entire amount into one bucket.
Count minimum debt payments among required obligations. Payments above those minimums belong in the savings and extra debt bucket for this framework. Count a dollar once. If retirement contributions have already been deducted from the take-home income you entered, do not pretend that same money is also available to spend from your checking account.
What if needs take more than half?
Suppose the essentials come to $2,500. That is 62.5% of a $4,000 income, and $500 above the original needs target. A calculator cannot make rent smaller. First record the real costs so the plan reflects your life.
One possible revised plan is $2,500 for needs, $900 for wants, and $600 for savings and extra debt. Those amounts still total $4,000. The tradeoff is visible: essentials get more room, and the other two buckets get less. This is an example of adjusting a plan, not a claim that these percentages suit everyone.
Make the first draft specific
Break the needs bucket into the bills and categories you actually pay. Give wants a limit you can check during the month. Split the savings bucket among named goals instead of leaving it as an unspecified leftover.
A monthly budget also needs a calendar. Having enough income over the whole month does not ensure the cash is there on the day rent is due. Keep an eye on pay dates and bill dates alongside these percentages.
- Enter monthly take-home pay in the calculator.
- Compare the needs result with your actual essential costs.
- Adjust the plan until all categories fit within income.
- Review it when your income, bills, or goals change.
Frequently asked questions
Does the 50/30/20 budget use gross income or take-home pay?
Use take-home pay, meaning the amount available after taxes and payroll deductions. If retirement savings is already deducted before that amount reaches you, do not count the same contribution again as money available in the 20% bucket.
What counts as a need in the 50/30/20 rule?
Needs are costs required for basic living or required payments, such as housing, basic groceries, essential transportation, insurance, utilities, and minimum debt payments. A category can contain both needs and wants, so splitting a bundled bill may be more accurate.
What if my needs are more than 50% of my income?
Record the real amount rather than forcing the label. Reduce wants where practical, review large fixed costs over time, and choose percentages that still add to 100%. In the worked example, a 62.5% needs share produces a valid 62.5/22.5/15 plan.
Are extra debt payments part of the 20% savings bucket?
Yes in this framework. Minimum required payments belong with needs. Amounts paid above the minimum belong with savings and extra debt payments because they improve your future financial position.
How does the rule work with biweekly pay?
You can base the regular budget on two paychecks per month and plan the two third-paycheck months separately. You can also use annual take-home pay divided by 12, but only if you keep the extra-paycheck money available for the months that use it.
Is 50/30/20 a requirement?
No. It is a starting framework. High housing costs, variable income, family needs, or aggressive debt goals can require different percentages. A useful budget reflects actual cash flow and makes its tradeoffs visible.
Sources and review notes
The calculations and scenarios in this guide are original BreadWinnr worked examples. We recalculated each example and checked that its parts match the stated total. Official sources support the financial concepts. Forum links document the reader problem that prompted the guide and are not treated as financial authority.
- CFPB: My spending rule to live by
- CFPB: Your Money, Your Goals toolkit, including cash flow budgeting
Read our research, testing, corrections, and source policy.
This guide provides general financial education. It does not account for your complete financial, tax, legal, or contractual situation.
Make the example yours.
Use the 50/30/20 budget calculator to try a different starting point.